Multi-Partner Firms: How to Align Your Partners Before You Go to Market
We have watched it happen often enough that it stopped feeling like bad luck. A deal that looked solid falls apart, not because the price was wrong or the buyer walked, but because one partner wanted something different from everyone else, and nobody surfaced that difference until a buyer was already at the table. A single partner can blow up a deal the rest of the partner group wanted, simply because goals and vision were never aligned in the first place.
That is not a story about a difficult personality. It is a story about a conversation that never happened early enough to matter. The good news is that this particular problem is entirely preventable, and prevention does not require every partner to want exactly the same thing.
Why Partner Alignment Determines Deal Success
Going to market with more than one partner means going to market with more than one definition of success, whether anyone has said so out loud or not. A firm can have strong financials, a clean client base, and real buyer interest, and still watch the process stall because the partners never agreed on what they were trying to achieve. Readiness in the financial sense and readiness in the human sense are two different things, and the typical sale process prepares only for the first. We think the second deserves equal attention, and earlier attention, because it is far cheaper to resolve before a buyer is involved than during a negotiation.
Where Partner Goals Diverge Before a Sale
The differences are predictable once you know to look for them. A partner close to retirement wants speed and certainty, a clean exit with the payout secured as soon as reasonably possible. A partner earlier in their career cares more about what happens after close, whether their role grows, shrinks, or disappears entirely under a new owner. Someone in between may be weighing a straightforward cash exit against staying invested in a rollover structure that pays off later if the combined firm performs.
None of these positions is wrong. They simply are not the same position, and a firm that assumes everyone wants the same outcome because everyone agreed to explore a sale is mistaking a shared decision to start for a shared definition of finished.
The Valuation Gap Few Firms Discuss
Even partners who agree on timing and structure can privately disagree on something just as consequential: what each of them contributed, and what that should be worth. Differences in equity stake, years of tenure, client relationships built, and day-to-day role inside the firm all shape a partner's sense of what is fair, and those senses do not always match the cap table. Left unaddressed, this becomes the kind of disagreement that surfaces at the worst possible moment, once real offer numbers are on the table and abstract fairness suddenly has a dollar figure attached to it.
Getting ahead of this means having the uncomfortable conversation about how proceeds will be allocated well before a term sheet forces the issue. A firm that waits until a buyer names a price to have that conversation is negotiating with itself and with a buyer at the same time, and it will lose ground on both fronts.
Building One Plan From Several Goals
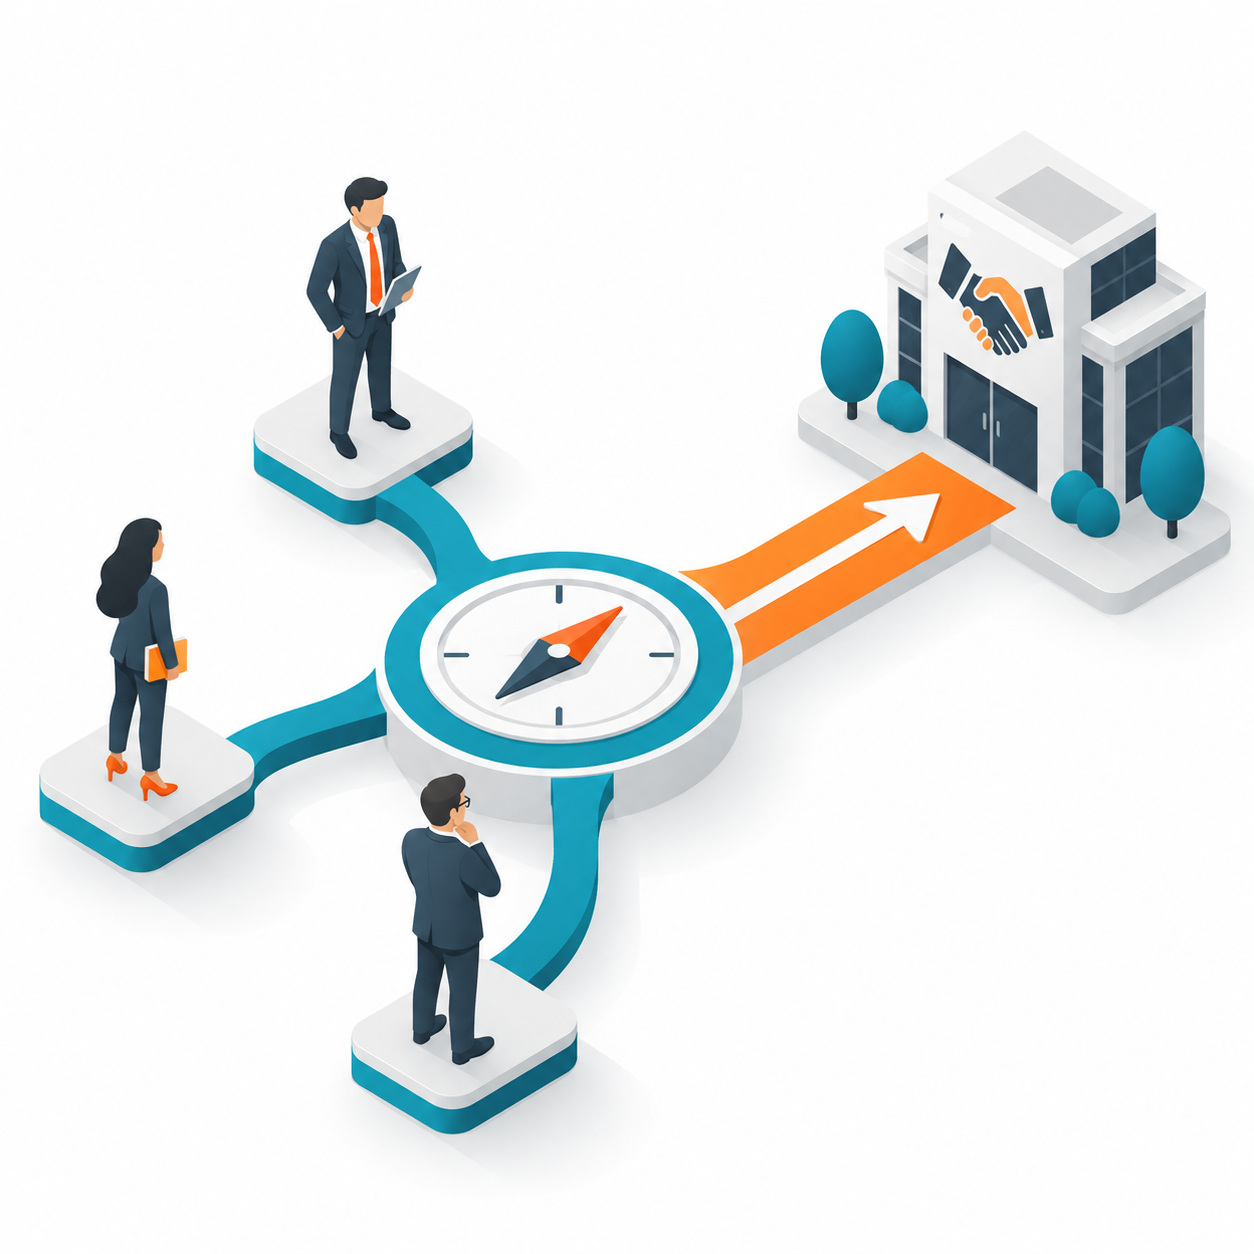
None of this means every partner needs to want the exact same thing. It means the firm needs a structured way to get every partner's real goals on the table, compare them honestly, and build a process that accounts for those differences instead of papering over them with a vague, shared enthusiasm for "exploring options." That structure can be as simple as a facilitated conversation where each partner states, in plain terms, what they want from a transaction and what they are not willing to accept.
Firms that do this early routinely discover their partners are more aligned than they feared, once assumptions get replaced with honest answers. Firms that skip it discover the opposite, usually partway through a process that is now harder to unwind than it would have been to prevent.
Why an Outside Perspective Helps
A neutral party in these conversations changes the dynamic in a way internal discussion cannot. Partners who have worked alongside each other for years bring history, old disagreements, and unspoken hierarchy into any conversation about money and control, even when everyone is trying to be reasonable. Someone outside that history can ask the direct questions a partner might hesitate to ask a colleague, and can name a gap in expectations plainly instead of letting it stay comfortably vague until it becomes a problem.
This is the conversation we have with partner groups before we ever talk about listing a firm, because an aligned partner group is the strongest predictor we see of a deal that closes on the terms everyone wanted. If your partners have agreed to explore a sale but have not yet agreed on what a successful one looks like, that is exactly the moment to talk with us.
Frequently Asked Questions About Multi-Partner Firm Sales
Why do multi-partner accounting firm sales fail more often than single-owner sales?
Multi-partner sales involve reconciling several partners' individual goals, timelines, and expectations about proceeds, and unresolved differences tend to surface only after a buyer is involved, when they are far harder and more costly to work through. A single-owner sale only has to satisfy one person's definition of a successful outcome.
What should partners agree on before starting a sale process?
At minimum, partners should align on their individual timing preferences, whether each partner wants a clean cash exit or is open to staying invested through a rollover structure, and how proceeds will be allocated across the partner group. Surfacing these points before talking to a buyer prevents them from becoming negotiating obstacles later.
How do partners typically disagree about proceeds from a firm sale?
Disagreements stem from differing views on what each partner's equity stake, tenure, client relationships, and day-to-day role should be worth, especially when those views were never explicitly discussed before a real offer put a specific number in front of the group.
Does every partner need to want the same outcome from a sale?
No. Partners can have different goals, some wanting an immediate clean exit and others wanting to stay involved through a transition or rollover, as long as the firm builds a structured process that accounts for those differences rather than assuming everyone wants the same thing by default.
When should multi-partner firms start discussing alignment before selling?
Ideally well before any buyer conversation begins, since misalignment is far easier and less costly to resolve internally than it is to work through once a deal is already in motion and real numbers are on the table.